 |
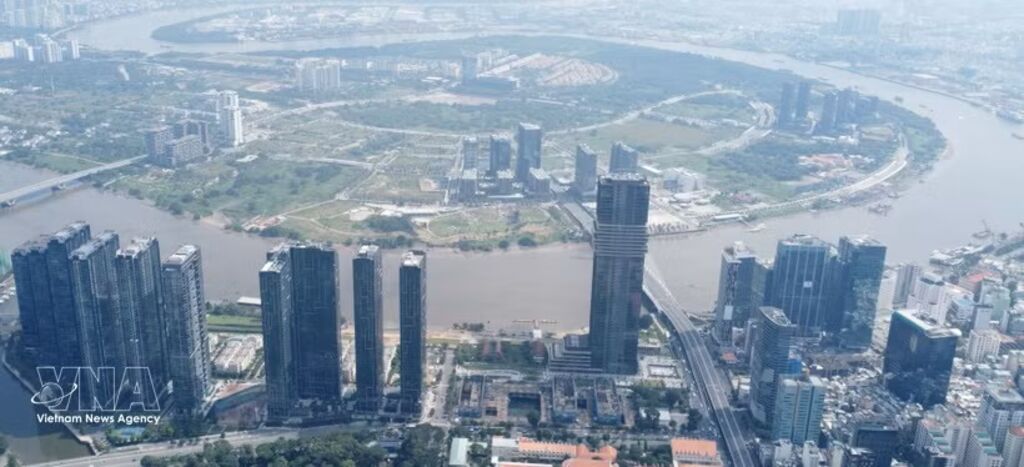
| The Thu Thiem peninsula, an area positioned as the core of Vietnam's international financial centre __Photo: VNA |
Deputy Prime Minister Nguyen Van Thang on October 2 signed Decision 1919/QD-TTg, revising and supplementing a number of provisions of Decision 412/QD-TTg dated March 31, 2022, which approved the scheme on improving Vietnam’s sovereign credit rating by 2030.
The decision updates several targets and key solutions of the scheme, with greater emphasis on science and technology, innovation and digital transformation.
Under the decision, Vietnam aims to become a developing country with modern industry and upper-middle income by 2030, while building a competitive and effective governance system and a dynamic economy driven by science, technology, innovation and digital transformation.
The country will continue improving its investment and business environment, enhancing the effectiveness of external relations and international integration, protecting the environment, adapting to climate change, reducing greenhouse gas emissions and promoting green, circular and low-carbon growth.
These efforts are expected to enhance Vietnam’s international position and reputation and facilitate an upgrade of its sovereign credit rating to investment grade, thereby helping reduce borrowing costs and sovereign credit risks.
The specific target is to achieve a sovereign credit rating of at least Baa3 by Moody’s or BBB- by S&P and Fitch by 2030.
For 2026-30, Vietnam targets average annual GDP growth of at least 10 per cent, with per capita GDP reaching around US$ 8,500 by 2030. Total social investment is expected to average around 40 per cent of GDP, with public investment accounting for 20-22 per cent.
The budget deficit is targeted at around 5% of GDP on average during the period, while public debt will be kept below 60% of GDP and government debt below 50 per cent of GDP.
In the banking sector, the minimum capital adequacy ratio of commercial banks is expected to approach Basel III standards and reach 8.625 per cent by 2030 at the latest. The country will also strengthen foreign exchange reserves when conditions permit.
Social and environmental targets include raising the Human Development Index (HDI) to around 0.8, maintaining forest coverage at 42 per cent, collecting and treating around 70 per cent of domestic wastewater in urban areas of grade-I and above by 2030, and reducing greenhouse gas emissions by 8-9 per cent.
The revised scheme calls for strengthening public finance, expanding sustainable revenue sources, improving debt indicators and consolidating fiscal stability. Fiscal policy will remain proactive, flexible and prudent, balancing economic growth support with medium- and long-term fiscal stability. Public debt management will be further improved by closely controlling debt growth and strengthening portfolio risk management, while potential liabilities arising from government guarantees, public-private partnerships and State-owned enterprises will be closely monitored.
The decision also stresses strengthening the banking system and modernising banking governance in line with international standards, including Basel III, while improving the transparency, accessibility, timeliness and quality of banking data.
Credit policy will be operated in line with macroeconomic and monetary market developments to control inflation, maintain macroeconomic stability and support sustainable growth. Credit will be channelled towards production, business activities, priority sectors and key growth drivers, while risks in potentially vulnerable areas will be tightly controlled.
The decision also calls for implementing solutions under Resolution 79-NQ/TW on developing the State-owned economic sector, focusing on improving the efficiency and governance of State-owned enterprises, promoting science, technology, innovation, digital transformation and green transition, and restructuring State capital in enterprises.
Relevant ministries and agencies are tasked with enhancing coordination with sovereign credit rating agencies and international organisations, improving the quality and frequency of official data published online, and taking a more proactive role in rating assessment meetings, conferences and forums.
Leaders of relevant ministries and agencies will directly oversee sovereign credit rating work within their respective sectors and participate in assessment sessions to provide clear, timely and convincing information to rating agencies and international organisations.- (VNA/VLLF)